Blockchain for business has attracted attention because it offers a different way for organizations to record transactions, share data, and verify information across multiple parties.
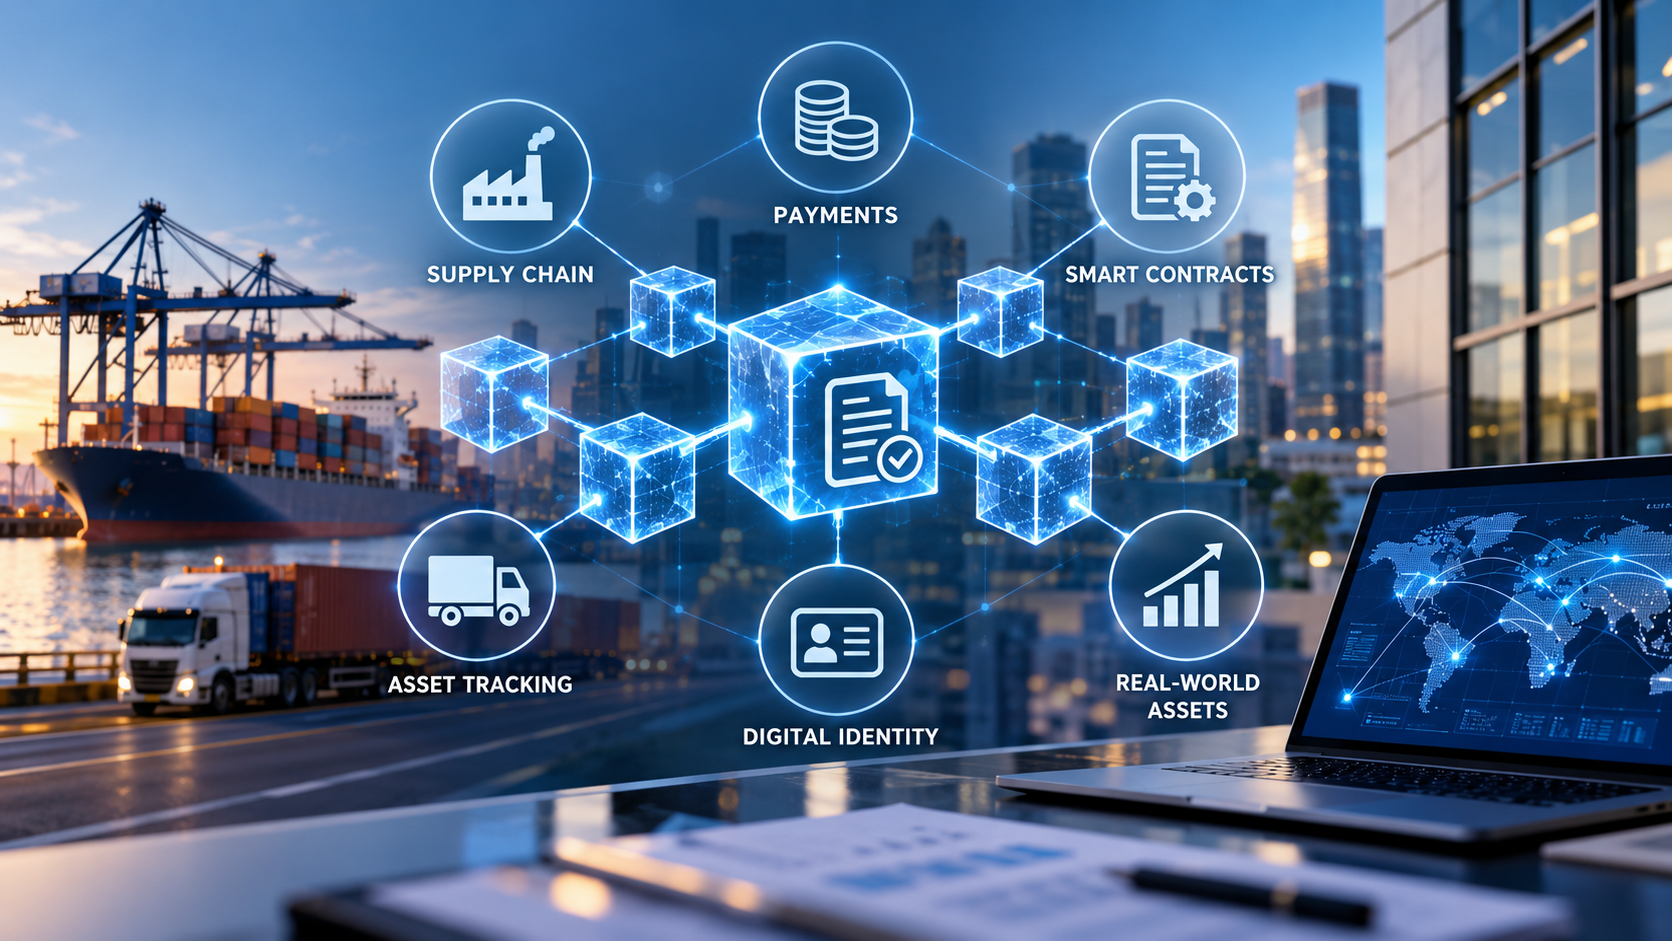
Although blockchain first became widely known through Bitcoin, business applications can extend beyond cryptocurrency. Companies have explored blockchain for supply chains, payments, digital identity, asset tracking, financial services, and other processes where several organizations need to share trusted records.
However, blockchain is not automatically better than a traditional database. Understanding where it provides practical value—and where it adds unnecessary complexity—is essential before adopting it.
What Is Blockchain for Business?
A blockchain is a type of distributed ledger that stores records across a network of participants.
Transactions are grouped into records and linked using cryptographic methods. Depending on the blockchain, participants may be able to verify transactions without relying on a single organization to maintain the entire ledger.
Business blockchains can be public, private, or permissioned.
Public blockchains allow broad participation, while permissioned networks restrict access to approved organizations or users.
For businesses, the important question is not simply whether blockchain can be used. It is whether a shared ledger solves a real business problem more effectively than existing technology.
Why Businesses Consider Blockchain
Traditional business processes often require multiple organizations to maintain separate databases.
For example, a manufacturer, shipping company, distributor, retailer, bank, and insurer may each maintain their own records for the same transaction.
Differences between these records can require reconciliation.
Blockchain can create a shared record that authorized participants can verify. In some situations, this may reduce duplicated record keeping and make it easier to trace transactions.
The potential benefits depend heavily on how the system is designed.
Supply Chain Tracking
Supply chain management is one of the most frequently discussed blockchain applications.
A product may pass through manufacturers, logistics companies, customs authorities, distributors, and retailers before reaching a customer.
A shared ledger can record events as goods move through this network.
Businesses may use these records to track information such as:
- Product origin
- Manufacturing events
- Shipping information
- Certifications
- Ownership transfers
- Delivery status
This can be useful when traceability is important.
However, blockchain cannot guarantee that information entered into the system is correct. If inaccurate information is recorded initially, the blockchain may simply preserve an inaccurate record.
Payments and Settlement
Blockchain networks can also be used to transfer digital assets or payment instructions.
Traditional cross-border payments may involve several financial institutions and settlement systems. Blockchain-based systems attempt to simplify some of these processes by allowing value or payment information to move through a shared network.
Stablecoins and tokenized deposits have increased interest in blockchain-based payment infrastructure.
Potential benefits can include faster settlement and greater availability outside traditional banking hours.
But businesses must also consider regulation, transaction costs, liquidity, custody, cybersecurity, and the reliability of the networks involved.
Smart Contracts and Business Automation
Smart contracts are programs that execute predefined instructions on a blockchain.
They can be used to automate certain transactions when specified conditions are met.
For example, a smart contract might release a digital asset after a transaction receives the required approvals.
Potential applications include:
- Payments
- Insurance processes
- Trade finance
- Asset transfers
- Escrow arrangements
- Digital marketplaces
Smart contracts can reduce some manual processes, but poorly designed code can create serious risks.
Software vulnerabilities, incorrect assumptions, and unreliable external data can all cause unexpected results.
Digital Identity and Credentials
Businesses frequently need to verify identities, qualifications, licenses, and other credentials.
Blockchain-based identity systems can allow organizations to issue digitally verifiable credentials.
Instead of repeatedly contacting the original issuer, another organization may be able to verify that a credential is authentic.
Possible applications include professional qualifications, educational certificates, membership credentials, and certain compliance processes.
Privacy remains critical. Sensitive personal information should not simply be placed permanently on a public blockchain.
Tokenization of Real-World Assets
Tokenization refers to representing rights or interests in an asset using digital tokens.
Assets being explored for tokenization include:
- Bonds
- Investment funds
- Real estate interests
- Commodities
- Financial instruments
- Other contractual rights
The goal is often to make issuance, transfer, settlement, or record keeping more efficient.
However, creating a token does not remove the legal requirements associated with the underlying asset.
Ownership rights, securities regulations, custody, taxation, and investor protection still matter.
Audit Trails and Record Integrity
Blockchain records can be difficult to alter once transactions have been confirmed.
This characteristic can make distributed ledgers useful for creating verifiable audit trails.
Organizations may use blockchain to document when records were created, transferred, or approved.
This does not mean that blockchain eliminates fraud.
A system can preserve a record of what was entered, but it cannot automatically determine whether every underlying event was legitimate.
Effective controls and independent verification may still be necessary.
Benefits of Blockchain for Business
When blockchain is appropriate for a particular process, several potential benefits may exist.
Shared Records
Multiple organizations can work from a common transaction history rather than maintaining completely separate records.
Traceability
Transactions can be followed through a sequence of recorded events, which may improve visibility across complex processes.
Automation
Smart contracts can automate some predefined actions and reduce manual processing.
Settlement Efficiency
Certain blockchain-based systems may reduce the time required to transfer or settle digital assets.
Verifiability
Cryptographic methods can help participants verify whether records have been altered.
These benefits are not guaranteed. They depend on network design, governance, data quality, and implementation.
Risks and Limitations
Businesses should evaluate blockchain with the same care applied to other critical technology.
Scalability
Some blockchain networks process transactions more slowly or at greater cost than centralized databases.
Privacy
Public blockchains can create challenges when businesses handle confidential or personal information.
Regulation
Legal requirements can differ by jurisdiction and by the type of asset or transaction involved.
Cybersecurity
Private keys, smart contracts, wallets, bridges, and other infrastructure can become targets for attackers.
Governance
A shared network needs rules covering upgrades, access, disputes, data standards, and participant responsibilities.
Integration Costs
Blockchain systems still need to connect with accounting software, enterprise systems, payment networks, and existing databases.
These integrations can be expensive and complex.
Blockchain vs. Traditional Databases
Not every business application needs blockchain.
A traditional database may be more appropriate when one trusted organization controls the system and participants do not need independent verification.
Blockchain becomes more relevant when multiple parties need to share records but do not want a single participant to have complete control over the database.
Before adopting blockchain, businesses should ask:
- Are multiple independent organizations involved?
- Do they need a shared record?
- Is reconciliation currently expensive or slow?
- Is tamper-resistant record keeping valuable?
- Can the same problem be solved more simply with an existing database?
If a conventional database solves the problem effectively, adding blockchain may provide little benefit.
Public vs. Permissioned Blockchains
Businesses can choose between different blockchain models.
Public networks generally provide greater openness and broad verification but may create privacy, performance, and governance challenges.
Permissioned blockchains restrict participation to approved entities.
This can provide businesses with greater control over access and governance while retaining some characteristics of distributed ledgers.
The appropriate model depends on the business problem rather than on the popularity of a particular blockchain.
How Businesses Should Evaluate Blockchain Projects
A blockchain project should begin with the business problem, not the technology.
Organizations should first identify the inefficiency they want to solve.
They can then evaluate whether blockchain provides measurable improvements in cost, speed, transparency, settlement, or coordination.
A small pilot may be more useful than immediately building a large production system.
Businesses should also consider cybersecurity, legal requirements, governance, interoperability, and long-term maintenance before deployment.
The Future of Blockchain for Business
Blockchain technology continues to evolve.
Some early enterprise blockchain projects failed to achieve widespread adoption, while other areas—particularly digital assets, tokenization, stablecoins, and settlement infrastructure—continue to develop.
Future adoption will likely depend less on whether blockchain is considered innovative and more on whether it can solve specific problems at a reasonable cost.
Businesses that adopt the technology successfully will need to combine blockchain with sound governance, cybersecurity, regulatory compliance, and reliable data.
Related Guides
- History of Cryptocurrency: From Bitcoin to Modern Crypto
- Bitcoin Price History: Major Milestones and Market Cycles
- Future of NFTs: Digital Ownership, Gaming and Real-World Assets
Official Resources
FAQs
What is blockchain for business?
Blockchain for business refers to using distributed ledger technology for commercial processes such as payments, supply chain tracking, asset transfers, digital credentials, and shared record keeping.
Does every business need blockchain?
No. Traditional databases are often simpler and more efficient when a single trusted organization controls the system.
Can blockchain prevent fraud?
Blockchain can make certain records difficult to alter, but it cannot guarantee that the original information entered into the system is accurate or legitimate.
What industries can use blockchain?
Financial services, supply chains, logistics, insurance, digital identity, asset management, and other industries involving shared records may explore blockchain applications.
What is the biggest challenge for enterprise blockchain?
There is no single challenge. Regulation, governance, privacy, cybersecurity, integration, scalability, and demonstrating a clear business benefit can all affect adoption.
Final Thoughts
Blockchain for business can provide useful tools for shared records, traceability, automation, digital assets, and settlement.
But blockchain should not be treated as a universal replacement for existing databases.
The strongest business applications are likely to be those where multiple organizations genuinely need a shared, verifiable record and where blockchain provides a measurable advantage over simpler alternatives.
For businesses, the key question is therefore not whether blockchain is the future, but whether it is the right technology for a specific problem.

 Bitcoin
 Ethereum
 Tether
 BNB
 XRP
 USDC
 Solana
 TRON
 Figure Heloc
 Zcash