

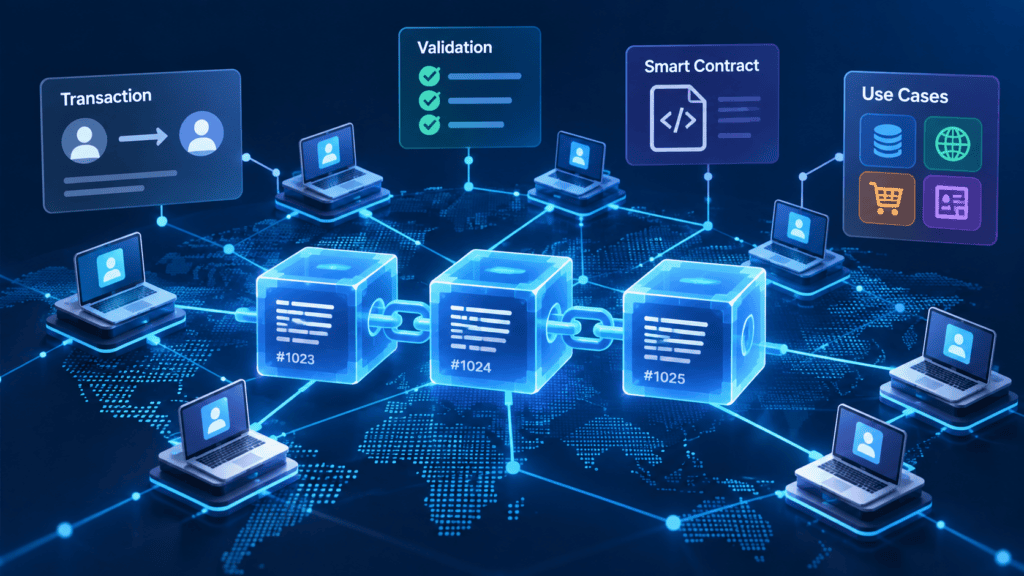
Blockchain basics begin with a simple idea: a blockchain is a shared digital ledger that records transactions or other information across a network of computers.
Bitcoin introduced blockchain technology to a broad audience, but blockchain can support much more than cryptocurrency. Developers and organizations now explore blockchain networks for digital assets, payments, smart contracts, decentralized applications, supply chains, and other systems that require shared records.
Understanding how blockchain works can make it easier to evaluate both its potential and its limitations.
What Is a Blockchain?
A blockchain is a type of distributed ledger.
Instead of relying on one organization to control a database, multiple computers, often called nodes, can maintain copies of the blockchain ledger.
The network records transactions according to its established rules. After the network confirms a transaction, it adds the record to the ledger, making unauthorized changes difficult.
Not every blockchain works in exactly the same way. Networks can differ in how they validate transactions, control access, store data, and reach agreement about the state of the ledger.
How Does Blockchain Work?
Although blockchain systems can be complex, the basic process can be understood in several steps.
1. A Transaction Is Submitted
A user initiates a transaction.
Depending on the network, this might involve transferring cryptocurrency, interacting with a smart contract, or recording other information.
2. The Network Receives the Transaction
The user sends the transaction to participants across the blockchain network.
Network computers check whether it follows the required rules.
3. Transactions Are Validated
Blockchain networks use a consensus mechanism to determine which transactions should be accepted.
Bitcoin, for example, uses proof of work. Many other networks use variations of proof of stake or other consensus systems.
4. Records Are Added to the Ledger
The blockchain records transactions after the network validates them.
In many blockchains, the network groups transactions into blocks. Each new block contains information that cryptographically connects it with earlier blocks.
This creates the chain of records that gives blockchain its name.
5. The Updated Ledger Is Shared
Participating nodes update their copies of the ledger according to the network rules.
This distributed structure allows participants to verify the transaction history without depending entirely on one central database.
Why Are Blocks Connected?
One of the key blockchain basics is the use of cryptographic hashes.
A hash is generated from data using a mathematical function. Even a small change to the original data generally produces a different hash.
Blocks can include the hash of previous blockchain data. This creates a cryptographic relationship between records.
Changing older information can therefore conflict with later records and the network’s consensus rules.
This is why confirmed blockchain records can be difficult to alter.
However, describing a blockchain as completely “immutable” can be misleading. The practical security of a network depends on its design, consensus mechanism, governance, and participants.
What Is Decentralization?
Decentralization means that control or record keeping is distributed rather than concentrated entirely in one organization.
Bitcoin allows many independent participants to verify the ledger according to the network’s rules.
Other blockchain systems may be much more centralized.
For example, a permissioned blockchain may allow only approved organizations to participate.
Blockchain should therefore not automatically be considered decentralized simply because it uses distributed ledger technology.
What Is a Consensus Mechanism?
A distributed network needs a way to agree on which transactions are valid.
This process is called consensus.
Two commonly discussed mechanisms are proof of work and proof of stake.
Proof of Work
Bitcoin uses proof of work as its consensus mechanism.
Participants known as miners use computing resources to compete to add new blocks. The system is designed to make altering the transaction history computationally difficult.
Proof of work can provide strong network security, but it requires substantial energy consumption.
Proof of Stake
Proof-of-stake networks select validators based on rules involving cryptocurrency committed to the network.
Ethereum transitioned from proof of work to proof of stake in 2022.
Different proof-of-stake systems use different technical and economic mechanisms, so we should not consider them identical.
Public and Private Blockchains
Blockchains can have different access models.
Public Blockchains
Public blockchains generally allow anyone to view the network and, depending on the protocol, participate in transactions or validation.
Bitcoin and Ethereum are prominent examples.
Private or Permissioned Blockchains
Permissioned blockchains limit participation to approved users or organizations.
Businesses may consider these systems when they need shared records but also require greater control over access, privacy, or governance.
The appropriate model depends on the purpose of the network.
What Are Smart Contracts?
Smart contracts are programs that execute instructions on a blockchain.
They can automatically perform actions when predefined conditions trigger them.
Ethereum and other programmable blockchain platforms widely support smart contracts.
They can support applications involving:
- Digital asset transfers
- Decentralized exchanges
- Lending protocols
- NFTs
- Games
- Tokenization
- Automated agreements
Despite their name, smart contracts are not necessarily legal contracts.
They are software, and errors in their code can create security and financial risks.
Blockchain and Cryptocurrency
Blockchain and cryptocurrency are related, but they are not the same thing.
A cryptocurrency is a digital asset that operates according to the rules of a blockchain or similar distributed network.
Bitcoin is both the name of a blockchain network and the cryptocurrency used within that network.
Other blockchains may support many different tokens and applications.
Organizations can also use blockchain technology in systems where cryptocurrency is not the primary purpose.
Common Blockchain Use Cases
Organizations and developers explore blockchain technology across several areas.
Cryptocurrency and Payments
Bitcoin demonstrated how users can transfer value through a decentralized network without a traditional central payment operator.
Other networks have expanded blockchain-based payments through cryptocurrencies, stablecoins, and other digital assets.
Decentralized Finance
Decentralized finance, commonly called DeFi, uses blockchain-based applications to provide services such as trading, lending, and borrowing.
These systems can operate through smart contracts, although they can also involve significant financial and technical risks.
Digital Ownership and NFTs
Non-fungible tokens can represent unique blockchain-based records.
Developers have used NFTs for digital collectibles, gaming assets, memberships, tickets, and experiments involving links to real-world assets.
Owning an NFT does not automatically mean owning copyright or other legal rights to the associated content.
Supply Chain Records
Blockchain can provide shared records among manufacturers, logistics companies, distributors, and other participants.
This may help with traceability when several organizations need access to the same transaction history.
However, blockchain cannot guarantee that information entered into the ledger was accurate in the first place.
Digital Credentials
Organizations can use blockchain-based systems to verify credentials, certificates, or other digitally issued records.
This can allow a recipient to check whether an authorized organization issued a credential.
Key Features of Blockchain
Several characteristics distinguish blockchain from conventional databases.
Distributed Records
Multiple participants can maintain copies of the ledger.
Cryptographic Verification
Cryptography helps protect transactions and connect blockchain records.
Consensus
Network rules determine how participants agree on valid transactions.
Transparency
Public blockchains can allow anyone to inspect transaction histories.
Transparency does not necessarily mean that the real-world identity behind every blockchain address is known.
Programmability
Some blockchains support smart contracts and decentralized applications.
These features can make blockchain useful for certain applications, but they also introduce new risks.
Blockchain Security
People sometimes describe blockchain as inherently secure, but the reality is more complicated.
A large blockchain network may make its transaction history difficult to manipulate. However, users can still lose assets through:
- Stolen private keys
- Phishing
- Malicious smart contracts
- Software vulnerabilities
- Exchange failures
- Wallet compromise
- Fraud and scams
Security therefore depends on much more than the blockchain ledger itself.
Users should distinguish between the security of a blockchain protocol and the security of the applications, exchanges, wallets, and services built around it.
Blockchain Limitations and Challenges
Blockchain is not the best solution for every problem.
Scalability
Some networks have limits on transaction capacity and may experience higher fees during periods of heavy demand.
Privacy
Public blockchain records can remain visible for long periods, creating privacy challenges for certain applications.
Energy Use
Proof-of-work systems can require substantial amounts of electricity.
Complexity
Blockchain applications may require specialized infrastructure, security practices, and technical expertise.
Regulation
Rules governing cryptocurrencies, digital assets, tokenized securities, and blockchain applications vary by jurisdiction and continue to evolve.
Data Quality
A blockchain can preserve information, but it cannot automatically determine whether information supplied from the real world is true.
Blockchain vs. Traditional Databases
One of the most important blockchain basics is understanding that a blockchain is not simply a faster version of a traditional database.
Traditional databases are often more efficient when one trusted organization controls the information.
Blockchain becomes more relevant when multiple independent participants need to share and verify records under common rules.
The choice should therefore depend on the problem being solved.
Using blockchain where a conventional database works well can add unnecessary cost and complexity.
How to Evaluate a Blockchain Project
Understanding blockchain basics can also help when evaluating a blockchain-based project, including the following questions:
- What problem does the blockchain solve?
- Why is a distributed ledger necessary?
- Who controls the network?
- How are transactions validated?
- How is the project governed?
- What are the security risks?
- Does the system rely on a token?
- What legal or regulatory requirements apply?
These questions can help separate practical applications from projects that use blockchain terminology mainly for marketing.
Related Guides
- Blockchain for Business: Uses, Benefits, Risks and Real-World Applications
- History of Cryptocurrency: From Bitcoin to Modern Crypto
- Bitcoin Price History: Major Milestones and Market Cycles
Official Resources
FAQs
What is blockchain in simple terms?
Blockchain is a shared digital ledger that allows participants in a network to record and verify transactions according to agreed rules.
Is blockchain the same as Bitcoin?
No. Bitcoin uses blockchain technology, but blockchain can support many other cryptocurrencies and applications.
Can blockchain records be changed?
Confirmed records can be difficult to alter, especially on large decentralized networks, but the degree of resistance depends on the design and security of the blockchain.
Does blockchain require cryptocurrency?
Not always. Public blockchain networks commonly use digital assets as part of their operation, while some private or permissioned systems may be designed for other purposes.
Is blockchain completely secure?
No technology is completely secure. Blockchain protocols can provide strong protections for transaction records, but wallets, applications, smart contracts, exchanges, and users can still be attacked or compromised.
Final Thoughts
Understanding blockchain basics means looking beyond cryptocurrency prices and technical buzzwords.
Blockchain combines distributed records, cryptography, consensus mechanisms, and—in some networks—programmable smart contracts.
These features can be useful when independent participants need to share and verify information without relying entirely on a single central database.
At the same time, blockchain introduces tradeoffs involving scalability, privacy, security, regulation, and complexity.
The most useful way to evaluate blockchain is therefore not to ask whether the technology will replace existing systems, but to understand how it works and determine where its particular characteristics provide a practical advantage.